From LinkedIn

Insights from the work.

Perspectives from Sergey Slitinskiy on investing, artificial intelligence, and business value.

Published on Sergey's personal LinkedIn profile. Collected here with links to the original posts and media.

Post artwork: DONT WAIT FOR LUCK, INCREASE ITS SURFACE AREA View media on LinkedIn
Investment StrategyLinkedIn

DONT WAIT FOR LUCK, INCREASE ITS SURFACE AREA

There is a fascinating idea from physics called ERGODICITY — and you don't need to understand the physics to understand what it might teach us about opportunity. Very loosely: given enough movement through a system, you experience more of the states that system makes possible. In other words, more repetitions effectively decrease your chance of failure. Now forget physics for a moment. Think about your life. Every conversation. Every room you enter. Every person you meet. Every idea you investigate. Every uncomfortable introduction. Every event you almost didn't attend. Every message you almost didn't send. Most lead nowhere. THAT'S THE POINT. Because occasionally, one changes everything. A conversation becomes a company. A stranger becomes an investor. An introduction becomes a customer. A random idea becomes intellectual property. A meeting you nearly skipped changes the next ten years of your life. We usually call that LUCK. But what if part of luck is simply EXPOSURE? You cannot control which door contains the opportunity. But you can control how many doors you open. Some humans continuously increase their surface area for luck. They meet. They ask. They build. They publish.…
Sergey Slitinskiy ·
Post artwork: YOUR SOFTWARE COMPANY MAY HAVE GREAT ARR BUT HOW MUCH OF IT SURVIVES AI? View media on LinkedIn
Investment StrategyLinkedIn

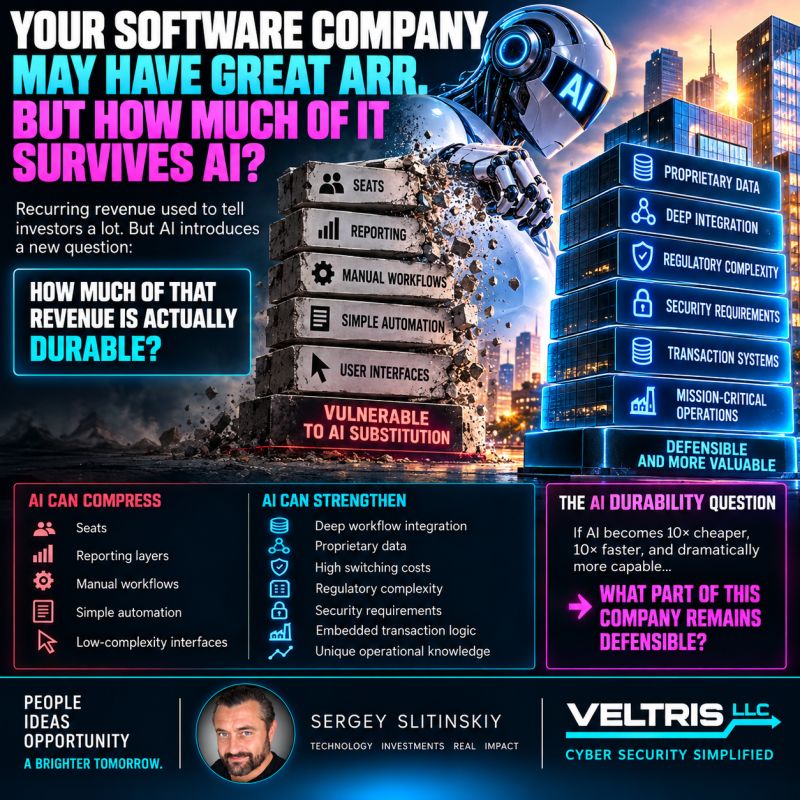
YOUR SOFTWARE COMPANY MAY HAVE GREAT ARR BUT HOW MUCH OF IT SURVIVES AI?

Recurring revenue used to tell investors a lot. Retention. Predictability. Customer dependence. Revenue quality. Those things still matter. But AI introduces a new problem to solve: HOW MUCH OF THAT REVENUE IS ACTUALLY DURABLE? Because not every software workflow is equally defensible. Some products are embedded deep inside: Mission-critical operations. Proprietary data. Regulated processes. Security controls. Transactional systems. Complex enterprise workflows. Others may simply be the current interface for getting a task done. And AI is getting very good at changing the interface. That creates a new question for private equity: ARE WE UNDERWRITING SOFTWARE... OR ARE WE UNDERWRITING A TEMPORARY WAY OF DOING THE WORK? That distinction matters. AI can compress: Seats. Reporting layers. Manual workflows. Simple automation. Low-complexity user interfaces. But it can also strengthen businesses with: → Deep workflow integration → Proprietary data → High switching costs → Regulatory complexity → Security requirements → Embedded transaction logic → Unique operational knowledge This is not simply an AI disruption story. It is a durability problem to solve. And it may require a new…

Sergey Slitinskiy ·
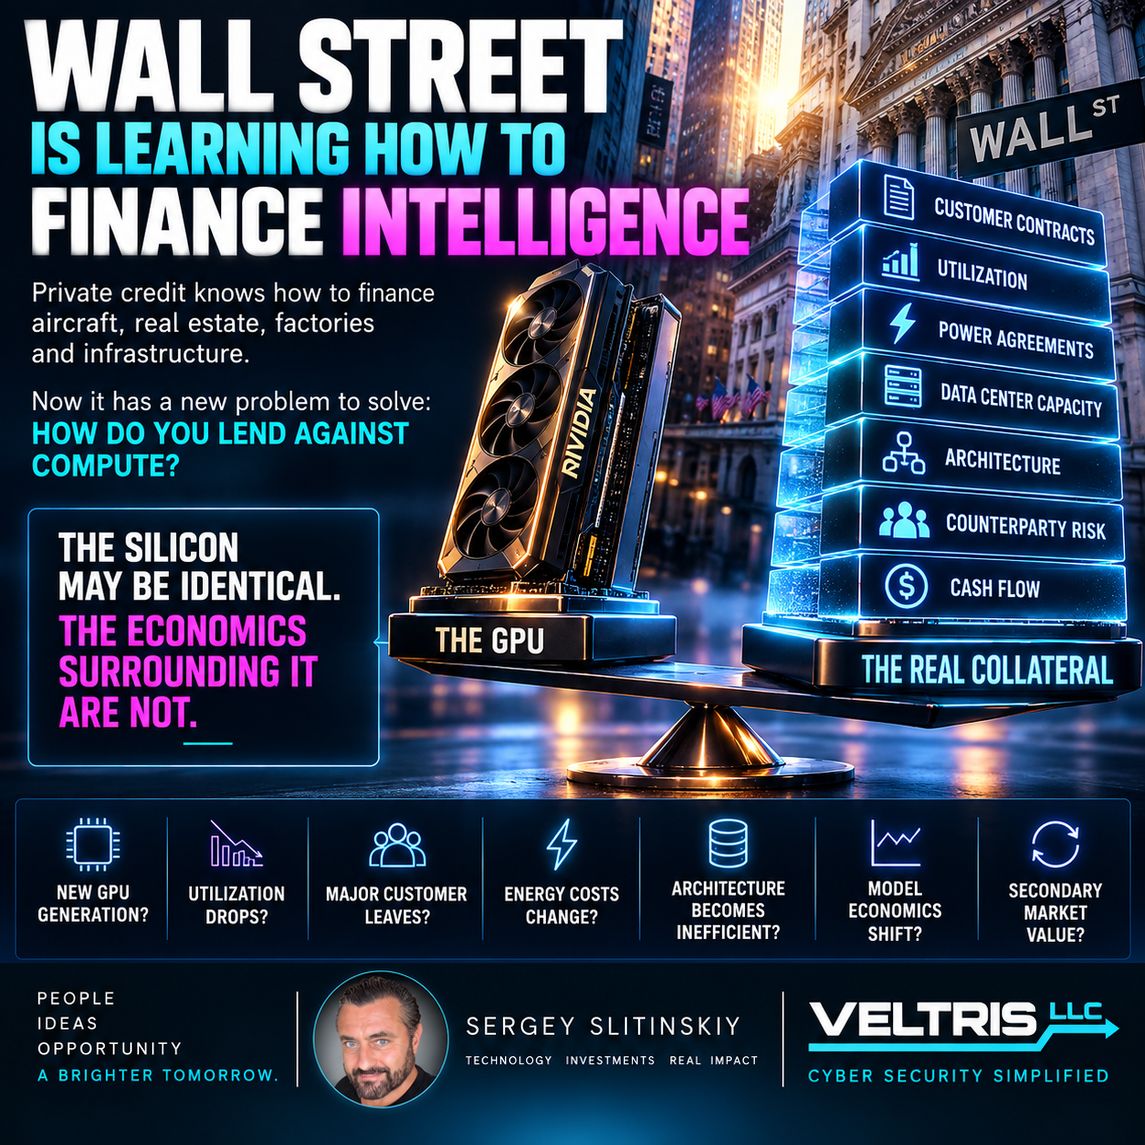
Post artwork: WALL STREET IS LEARNING HOW TO FINANCE INTELLIGENCE View media on LinkedIn
Investment StrategyLinkedIn

WALL STREET IS LEARNING HOW TO FINANCE INTELLIGENCE

Private credit already knows how to finance: Aircraft. Real estate. Factories. Infrastructure. Now it has a new problem to solve: HOW DO YOU LEND AGAINST COMPUTE? More than $20 billion of GPU-backed financing facilities have already been announced. And Nvidia is reportedly exploring ways to help insurers protect lenders financing AI infrastructure. That tells us something important. THE GPU IS BECOMING A FINANCIAL ASSET. But here is where it gets interesting. The GPU itself may not be the most important collateral. The real value may sit around it. The customer contract. The utilization. The power agreement. The data-center capacity. The architecture. The counterparty. And ultimately... THE CASH FLOW. Two companies can own essentially the same GPUs and represent completely different credit risks. Why? Because the silicon may be identical. The economics surrounding it are not. That creates a fascinating new problem for investors to solve: HOW DO WE UNDERWRITE THE ARCHITECTURE AROUND COMPUTE? What happens when: → A new GPU generation arrives? → Utilization drops? → A major customer leaves? → Energy costs change? → The architecture becomes inefficient? → Model economics shift? → The…

Sergey Slitinskiy ·
Post artwork: PRIVATE EQUITY HAS A $518 BILLION AI PROBLEM TO SOLVE View media on LinkedIn
Investment StrategyLinkedIn

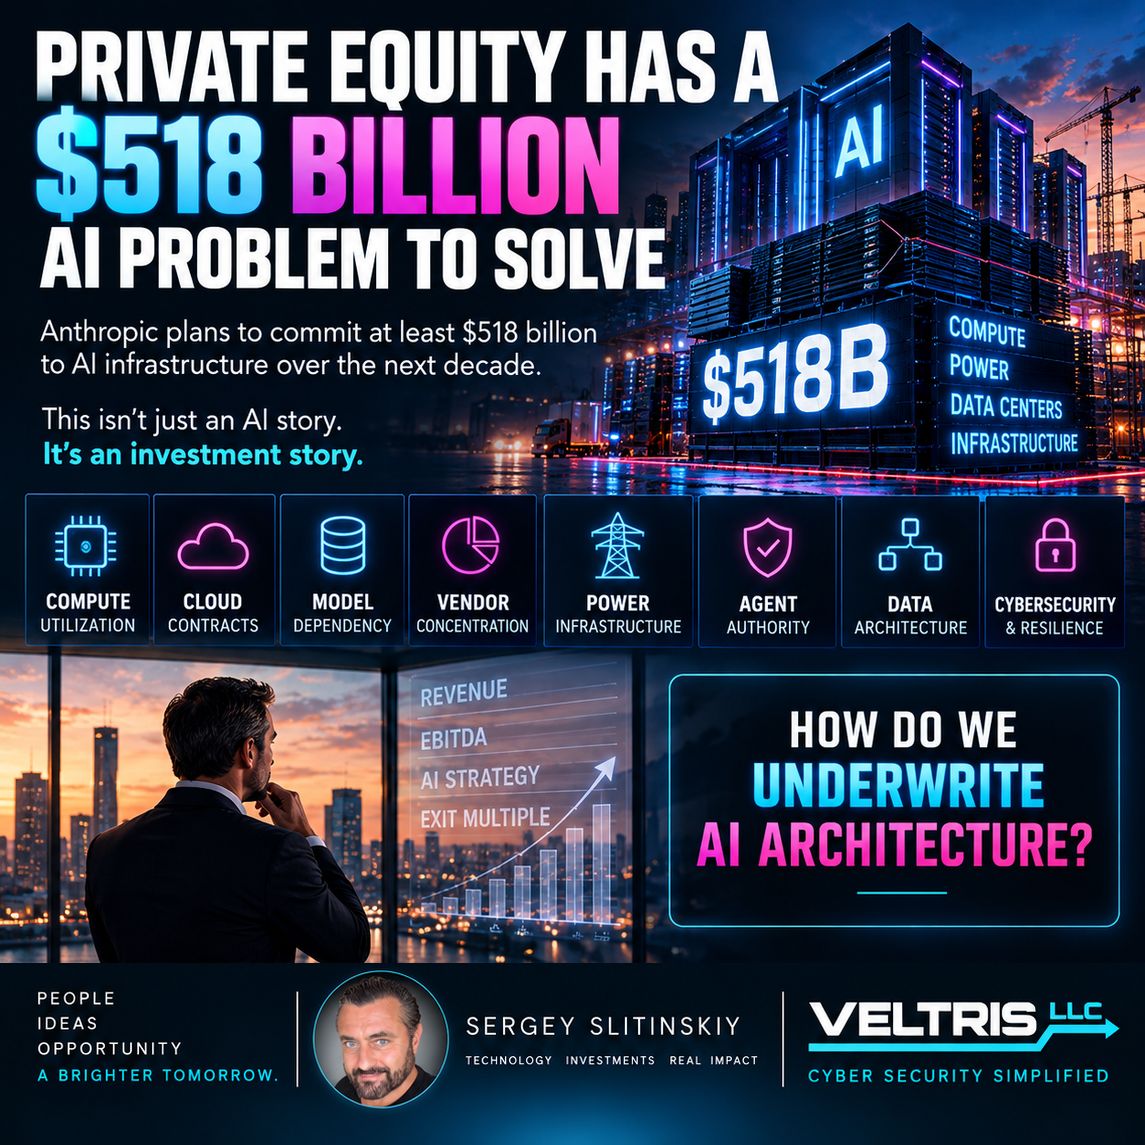
PRIVATE EQUITY HAS A $518 BILLION AI PROBLEM TO SOLVE

Anthropic plans to commit at least $518 billion to AI infrastructure over the next decade. That number is enormous. But the more interesting question is: WHAT DOES IT TEACH INVESTORS? — AI ARCHITECTURE IS BECOMING CAPITAL ARCHITECTURE. Compute. Cloud contracts. GPU utilization. Power. Model dependency. Vendor concentration. Data architecture. Agent authority. Cybersecurity. These used to look primarily like technology decisions. Increasingly, they are investment decisions. — AND THAT CREATES A NEW PROBLEM TO SOLVE: HOW DO WE UNDERWRITE AI ARCHITECTURE? A company can have strong revenue. Strong EBITDA. Excellent management. A compelling AI strategy. And still sit on an architecture that requires enormous future capital. One that depends heavily on a single provider. One that is difficult to migrate. Or one that creates operational dependencies the next owner will inherit. — AI DUE DILIGENCE SHOULD NOT STOP AT: “Does this company use AI?” It should start asking: → How much compute does the business actually require? → How portable is the architecture? → Where are the concentration points? → Who controls the models and data? → What authority has been transferred to AI agents? → What…

Sergey Slitinskiy ·
Post artwork: THE BEST DEAL YOUR FIRM NEVER SAW View media on LinkedIn
Investment StrategyLinkedIn

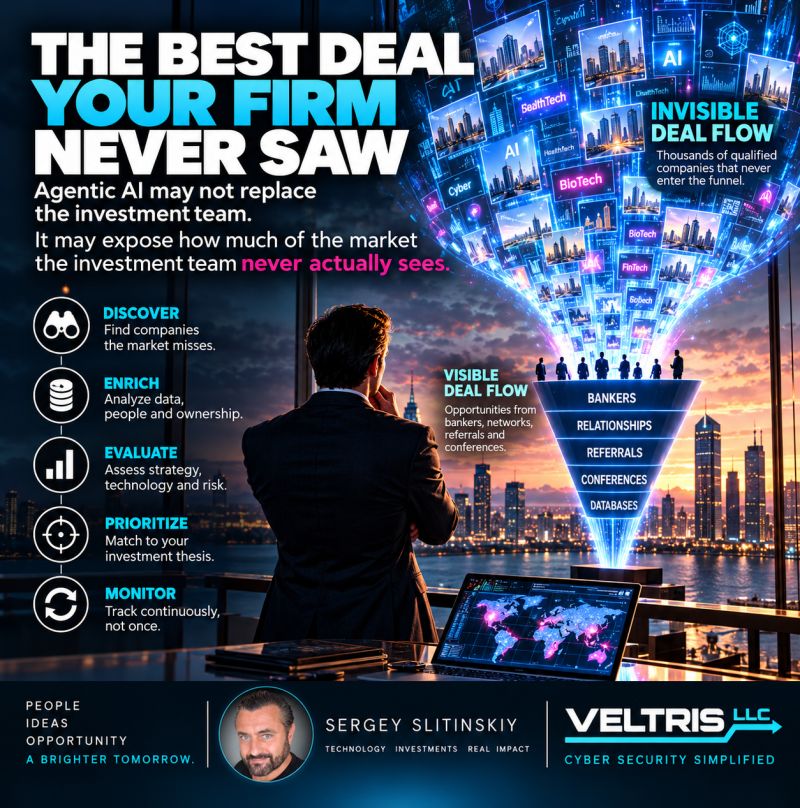
THE BEST DEAL YOUR FIRM NEVER SAW

Agentic AI may not replace the investment team. It may expose how much of the market the investment team never actually sees. ──────────── Traditional deal sourcing has a hidden limitation: HUMAN BANDWIDTH. Bankers bring opportunities. Partners bring relationships. Conferences create introductions. Networks generate referrals. Analysts search databases. All of these channels can work extremely well. But they still determine which companies enter the funnel in the first place. ──────────── We spend enormous effort asking: “Which company should we invest in?” Maybe AI creates a more uncomfortable question: WHY DID THESE COMPANIES MAKE IT INTO THE FUNNEL — WHILE THOUSANDS OF OTHERS NEVER DID? ──────────── This is where Agentic AI gets interesting. Imagine agents continuously: • Discovering companies • Enriching company data • Mapping founders and ownership • Identifying competitors • Analyzing growth signals • Examining technology architecture • Measuring founder dependency • Detecting operational weaknesses • Comparing companies against an investment thesis Not once. Continuously. ──────────── That creates something I think investment firms should start measuring: THE INVISIBLE…

Sergey Slitinskiy ·
Post artwork: THE CONVICTION-LEVERAGE PARADOX View media on LinkedIn
Investment StrategyLinkedIn

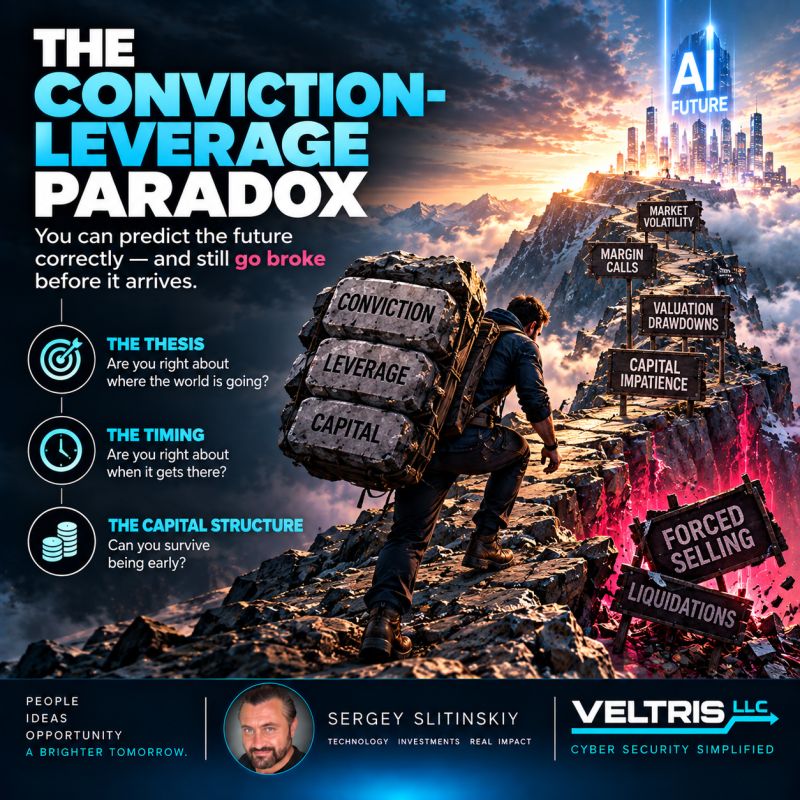
THE CONVICTION-LEVERAGE PARADOX

You can predict the future correctly... ...and still go broke before it arrives. ──────────── This may be one of the most misunderstood risks in AI investing. We spend enormous amounts of time asking: Is the thesis right? Is AI really this transformative? Will compute demand continue? Will infrastructure spending explode? Which companies will capture the value? But there is another question that may matter just as much: CAN YOUR CAPITAL SURVIVE THE JOURNEY? ──────────── Because there are really three different bets being made. THE THESIS Are you right about where the world is going? THE TIMING Are you right about when it gets there? THE CAPITAL STRUCTURE Can you survive being early? ──────────── Those are not the same thing. You can correctly identify a technological revolution... ...and still structure the investment incorrectly. You can identify the right companies... ...and still enter at the wrong valuation. You can correctly predict enormous long-term demand... ...and still use enough leverage that a temporary drawdown destroys the position. ──────────── This creates what I call: THE CONVICTION-LEVERAGE PARADOX. The stronger our conviction becomes, the more comfortable we…

Sergey Slitinskiy ·
Post artwork: AI DIDN’T CREATE THE SOFTWARE DEBT PROBLEM. View media on LinkedIn
Investment StrategyLinkedIn

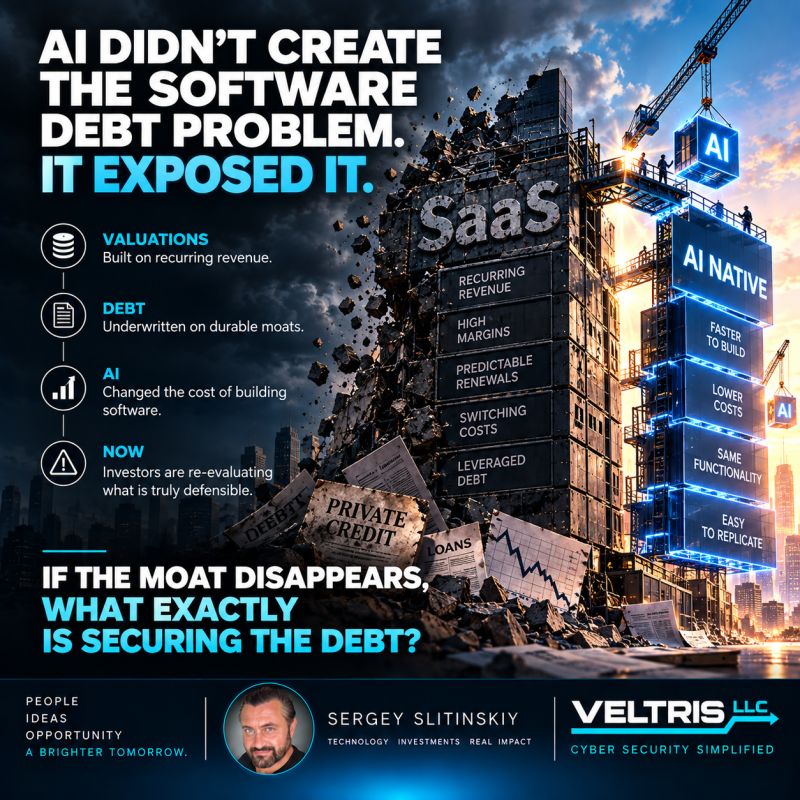
AI DIDN’T CREATE THE SOFTWARE DEBT PROBLEM.

IT EXPOSED IT. ──────────── For years, software looked like one of the safest places to put leverage. Recurring revenue. High margins. Low capital intensity. Predictable renewals. High switching costs. Those characteristics didn’t just support software valuations. They supported the DEBT behind those valuations. ──────────── Then AI changed something fundamental. Not necessarily the software itself. It changed the assumption about how difficult that software is to replace. If an AI-native competitor can reproduce 70% of a product’s functionality faster and cheaper, the question is no longer simply: “Will customers leave?” There is another question: WHAT HAPPENS TO THE DEBT THAT WAS UNDERWRITTEN AGAINST THE OLD MOAT? ──────────── This is where it gets interesting. A software company can still have recurring revenue, positive EBITDA, strong retention and plenty of customers... ...while its competitive architecture is quietly deteriorating. The financial statements tell us what the company earned yesterday. They don’t necessarily tell us how reproducible its advantage has become tomorrow. ──────────── Maybe AI due diligence needs to go deeper than revenue growth, churn and EBITDA.…

Sergey Slitinskiy ·
Post artwork: A PROFITABLE COMPANY CAN STILL BE BANKRUPT. View media on LinkedIn
Investment StrategyLinkedIn

A PROFITABLE COMPANY CAN STILL BE BANKRUPT.

Not financially. Architecturally. A company can have strong revenue, healthy EBITDA, growing customers and great management — while underneath it sits a technology architecture that can no longer support where the business needs to go. I call this Architectural Bankruptcy. It rarely happens overnight. It accumulates through years of shortcuts: legacy systems nobody wants to touch, critical integrations understood by one person, APIs without clear ownership, duplicated data, unmapped SaaS dependencies and security controls added after the fact. Then AI arrives. And companies begin connecting agents to an architecture they already struggle to understand. The business still works. The problem appears when you try to CHANGE it. → Acquire another company? Integration takes 6 months. → Launch a new product? 9 months. → Replace a critical platform? Too dangerous. → Deploy AI across the enterprise? Nobody can clearly explain what it will touch. And that raises a question I think investors should be asking: Should technical architecture be part of enterprise value? Imagine two companies with the same revenue, same EBITDA and similar market position. Company A can launch a new product in…

Sergey Slitinskiy ·